< Back to Finance and Delivery Guide
For larger scale projects such as New Towns, significant up-front public sector investment is essential. For new Garden Cities at all scales today, it is likely that most of the investment in creating a new Garden City will come from the Private Sector and will require a blended strategy to finance different elements on different risk and return rates. The private investment will dwarf the public investment in the social housing, schools, health centres, other community facilities, as well as infrastructure such as roads and utilities, not least given the private utilities sector. While much of this public investment must come first in order to enable the private investment in homes for sale, etc to be realised, private mortgage finance of individual householders is the backbone supporting the delivery of a new Garden City. Institutional investors, bond investors and pension funds acting in property, alongside traditional large housing developers/large registered social landlords are potential sources of private investment in a new community. Institutional investors seek a relatively low return over the medium and long term – providing patient capital – as long as it is secure.
Housebuilders
Large housing developers are often considered the default source of private investment in new Garden Cities because they have the financial resources and expertise in major project delivery. Increasingly they hold land in their reserves at the scale necessary for new Garden Cities, acting as land promoters and then selling some plots to other housebuilders and delivering others themselves. However, their investors expect strong financial returns over a relatively short period and new Garden City may not meet their investment criteria in this respect. Securing the financing of even the basic infrastructure necessary to enable a sites development can be challenging.
Master developers
Master developers frequently source capital from the markets to inject into schemes, both to pay for land and for infrastructure and delivery costs. Some master developers may have their own cash reserves as well. Given the long term investment horizons required for new Garden Cities, their capital stack will typically be designed quite differently to traditional housebuilders, drawing on pension funds, insurance companies, family offices and real estate investment trusts. Some may also be publicly listed thereby benefiting from rights issues and other share capital. They may also seek investment from private equity markets.
Registered providers
In many respects, registered providers RPs are ideal partners for building new Garden Cities, not least as they retain ownership of some of their housing stock and so have a long term interest in sites that can mean they take on a long term stewardship role. They operate on longer term timeframes than traditional housebuilders in terms of rates of return, and can access grant funding themselves directly. They are also familiar with working closely with local and strategic authorities. With the shift towards major forward funding deals and a wider mix of tenures including intermediate housing and purpose built rented homes, RPs are increasingly involved in new Garden Cities from an early stage, and in in number of cases are acting as master developer and/or strategic land promoter for major schemes such as Tendring Colchester Borders Garden Community. Recent changes in regulation also mean that housebuilders can also setup a registered provider themselves.
Infrastructure contractors
Large scale infrastructure contractors may also bring capital to schemes, but in a different way to other investors. As they are not trying to become long term stewards of land, this deployment will focus on securing work and accelerating projects, as well as profit sharing via joint ventures. This may enable deferred payment for roads, utilities and drainage, including over several years, improving cashflow by tying payments to parcel sales or other development milestones. This may entail a formal equity stake in a project.
Bond issues
Bond issues are used throughout the world, and in Britain historically, to raise capital for major infrastructure and development projects. The University of Cambridge issued £350m worth of bonds for 40 years, at a coupon of 3.75%, to capitalise its plan for the North West Cambridge Urban Extension at Eddington, including 50% subsidised housing for staff and students. The university benefited from a triple A credit rating, placing its borrowing costs close to that of the government. In 2018, further bonds were issued worth £600m, over 60 years to finance the second phase of the project. Such bonds could be used in future to pay for infrastructure in new Garden Cities, but would require suitably stable institutions to issue them.
Institutional investors and Government debt guarantees
Homes England’s wholly-owned subsidiary, the National Housing Bank, will be launching an expanded guarantee platform that responds flexibly to market needs. These products are designed to attract investment into housing and regeneration across a broad range of formats, tenures and regions. They work as targeted interventions to unlock new investment, while earning an appropriate risk-adjusted return. This builds on earlier work by MHCLG around the Affordable Homes Guarantee Scheme.
One of the advantages of a development corporation would be flexibilities in relation to making funding deals that a local authority by virtue of prudential regulation could not attain. However, in formulating a funding strategy for the actual development of the infrastructure for a Garden City, local authorities should not necessarily see institutional finance as the primary or most desirable option. The local authority must be confident that private investors will offer terms that are preferable to those available through borrowing or public finance institutions such as the National Housing Bank. This will include consideration of: the cost of finance; the length of time before loans or bonds have to be repaid; and the conditions that the lender will impose on the LDV or the local authority.
It is particularly important to clarify the last of these since some conditions (eg options to call in loans at fixed dates), may be barriers to proper completion of the new Garden City over the long term. It may emerge that a combination of public and private finance with the public sector taking on the risks that it is most able to manage; this would leave private investors less exposed and thus able to offer better terms. Overall, for viable projects, the availability of funds from both the public sector and the private sector should not be a barrier to the successful development of a new Garden City. In practice however, the site specific risks and wider economic uncertainty play a factor in securing this.
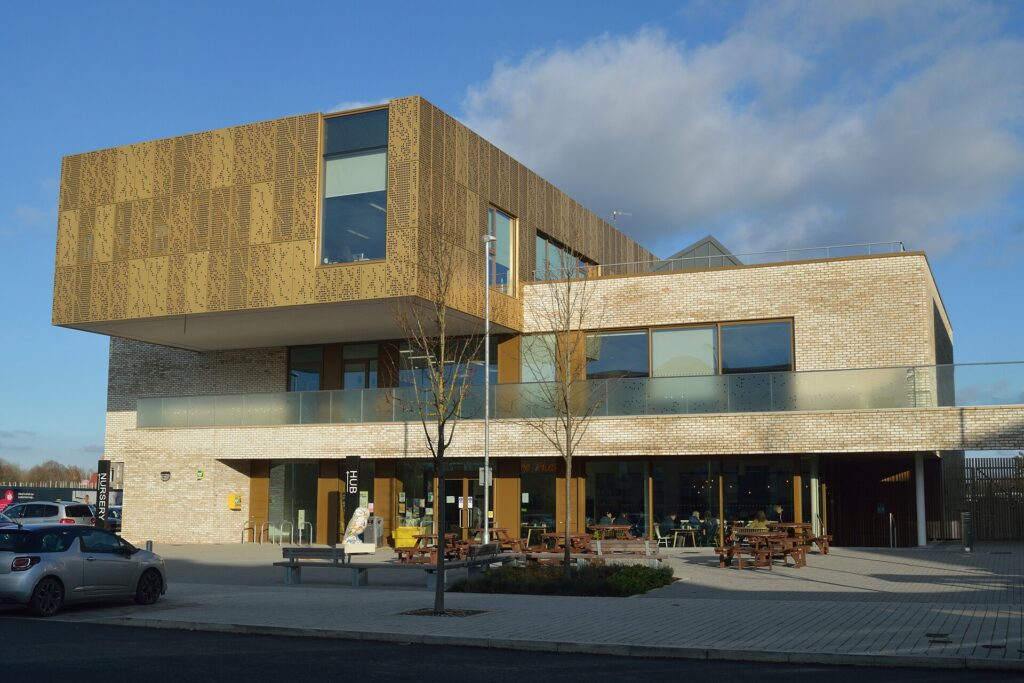
Mulberry Park, although just 850 homes, has been delivered by the housing association Curo as master developer, working with Bellway Homes. Their long term investment in the site, including co-locating their offices there, enabled the delivery of a substantial community use beyond what was required by the planning permission. Credit – RWendland CC